Business Sale CGT Calculator
Estimate Capital Gains Tax when selling your business using Business Sale CGT Calculator. Includes all 4 small business concessions 15-year exemption, active asset reduction, retirement exemption & rollover. ATO-aligned.
🏢 Business Sale CGT Calculator — Australia
Estimate Capital Gains Tax on selling your business. Includes small business CGT concessions — 15-year exemption, 50% active asset reduction & retirement exemption.
Capital Gains Tax When Selling a Business
When you sell your business whether it’s the goodwill, business assets, or shares in a company the profit is generally subject to Capital Gains Tax (CGT). CGT is not a separate tax in Australia; the gain is added to your assessable income and taxed at your marginal rate.
The good news: Australian small business owners have access to four powerful CGT concessions that can reduce or even eliminate tax on the sale. To access them, your business must meet the basic eligibility conditions either the small business entity test (aggregated turnover under $2 million) or the maximum net asset value (MNAV) test ($6 million or under).
Understanding which concessions apply to your situation can save tens of thousands of dollars. Use our calculator below to estimate your position.
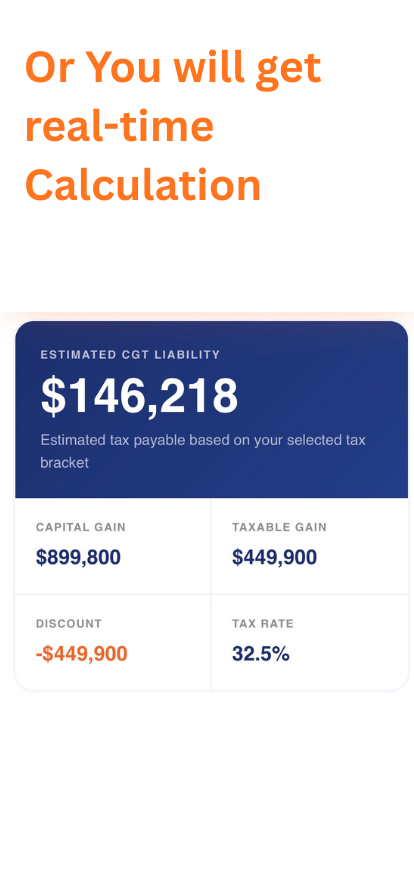
Try Business Sale CGT Calculator for free to get most accurate estimates.
How to calculate CGT on Business Sale CGT Calculator
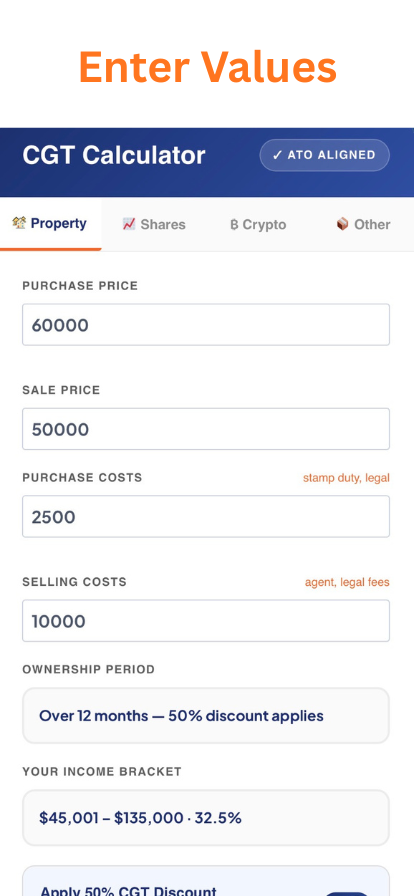
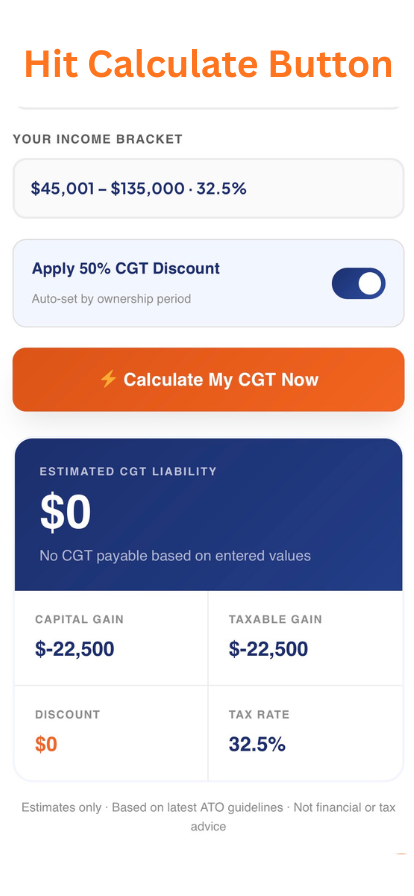
Step by step guide on Business Sale CGT Calculator
4 Ways to Reduce Your Business Sale CGT
Applied in order each concession can reduce your gain further. You may qualify for more than one.
Or check ATO’s Official Site for comprehensive information.
Concession 1
15-Year Exemption
If you’ve continuously owned the active asset for 15+ years and are aged 55+ retiring (or permanently incapacitated), your entire capital gain is exempt. This is applied first if it applies, no other concessions are needed.
Concession 2
50% Active Asset Reduction
Reduce your capital gain by 50% on active business assets. This stacks on top of the general 50% CGT discount if held 12+ months meaning your effective gain can be reduced to just 25% of the original gain.
Concession 3
Retirement Exemption
Exempt up to $500,000 of capital gains over your lifetime. If you’re under 55, the amount must be contributed to superannuation. If 55 or older, you can keep the proceeds without contributing to super.
Concession 4
Small Business Rollover
Defer your capital gain by rolling it into replacement active assets purchased within 2 years. This doesn’t eliminate the gain, it delays it, giving you time to reinvest and restructure before paying tax.
How Business Sale CGT is Calculated
Four inputs in Business Sale CGT Calculator, one result your estimated tax bill in under a minute.
Enter Sale Price
What did you sell the property for? Include all proceeds from the sale.
Add Cost Base
Include stamp duty, legal fees, inspections, and improvements. This reduces your capital gain.
Check Holding Period
Held 12+ months? You get a 50% discount on your capital gain. Huge savings!
Calculate Your Tax
Your income determines your tax rate. We add the capital gain to your taxable income.
Do You Qualify for Small Business CGT Concessions?
Basic Conditions, You Must Meet ONE of:
✅ Small business entity test aggregated annual turnover under $2 million |
✅ Maximum net asset value (MNAV) test net assets $6 million or less |
✅ Asset is an active asset (used or held ready for use in a business) |
✅ Active asset test satisfied for at least half the ownership period |
Common Reasons You May NOT Qualify:
❌ Asset is primarily used to derive rent, interest, or royalties |
❌ Turnover exceeds $2M AND net assets exceed $6M |
❌ Asset acquired before 20 September 1985 (pre-CGT asset) |
❌ Company fails the 80% active asset test for shares concession |