Capital Gains
Tax CGT Calculator
Australia
Just sold your property/assets in Australia? Get a precise CGT estimate aligned with the latest ATO guidelines. No signup, completely free CGT Calculator.
CGT Calculator
Enter your details for an instant Capital Gains Tax estimate. Free · No signup · ATO-aligned.
⚠️ This is an estimate for general information only. It is not tax advice. Consult a registered tax agent for your personal circumstances.
🚨 2026 Federal Budget Major CGT Changes from 1 July 2027
The May 2026 Federal Budget announced the biggest change to Australian CGT in decades. From 1 July 2027, the current 50% CGT discount will be replaced by cost-base indexation (only real gains above inflation are taxed) plus a 30% minimum tax rate on those gains. Properties purchased on or before 12 May 2026 are grandfathered, the 50% discount continues to apply for pre-existing holdings. New residential builds from 1 July 2027 may choose whichever method delivers the lower tax. This calculator reflects current 2025–26 rules. Speak to your accountant about whether selling before 1 July 2027 makes sense for your property.
ATO Aligned
No Data Stored
All Asset Types
Instant Results
No Signup Required
Completely Free
Why Calculate your CGT Early?
Many Australians miss out on thousands of dollars simply because they did not calculate their CGT before selling. CGT tax calculation early gives you time to plan. With that planning, you can make a significant difference to your final tax bill.
Claim the 50% CGT Discount
Hold an asset for more than 12 months before selling and you may qualify for a 50% CGT discount under ATO rules halving the taxable portion of your gain.
Control Your Tax Timing
Delaying a sale until after 30 June pushes your capital gain into the next financial year, giving you extra time before the liability hits your tax return.
Build an Accurate Cost Base
Gather all records early e.g. stamp duty, renovation invoices, legal fees. A higher cost base means a lower capital gain and less tax to pay. Get precise estimate from our CGT Calculator
Offset with Capital Losses
CGT Tax Calculator early gives you time to sell underperforming assets before 30 June and use those losses to offset your capital gains.
Avoid a Surprise Tax Bill
CGT Tax Calculator added to your taxable income and assessed in your annual tax return. Without planning, investors are often caught off guard.
Plan Super Contributions
Making a concessional super contribution before 30 June reduces your taxable income directly lowering the rate at which your capital gain is taxed.
What Is Capital Gains Tax in Australia?
Capital Gains Tax (CGT) is the tax you pay on the profit made when you sell or dispose of an asset such as an investment property, shares, or cryptocurrency for more than you originally paid for it. The capital gain is added to your taxable income and taxed at your marginal income tax rate according to ATO rules.
In short, you pay CGT whenever you sell an asset at a profit. However, you may be exempt in certain situations such as selling your main residence or assets acquired before 20 September 1985. You can use CGT Calculator for accurate estimate.
Example — Investment Property
Purchase price | $500,000 |
Sale price | $850,000 |
Capital gain | $350,000 |
After 50% discount (held 3+ years) | $175,000 |
Taxable gain added to income | $175,000 |
🔑 Key Points
CGT applies to investment properties, shares, crypto, business assets and most other assets
CGT does not apply to your primary home under the main residence exemption
Assets held for more than 12 months qualify for the 50% CGT discount for individuals
Capital losses can reduce your capital gain in the same or future financial years
CGT is reported to the ATO in your annual income tax return
CGT is not a flat tax — your gain is added to income and taxed at your marginal rate
How to calculate CGT
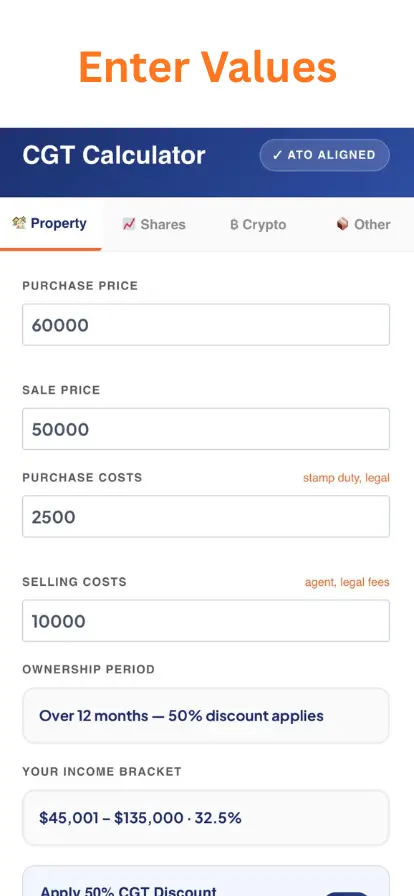
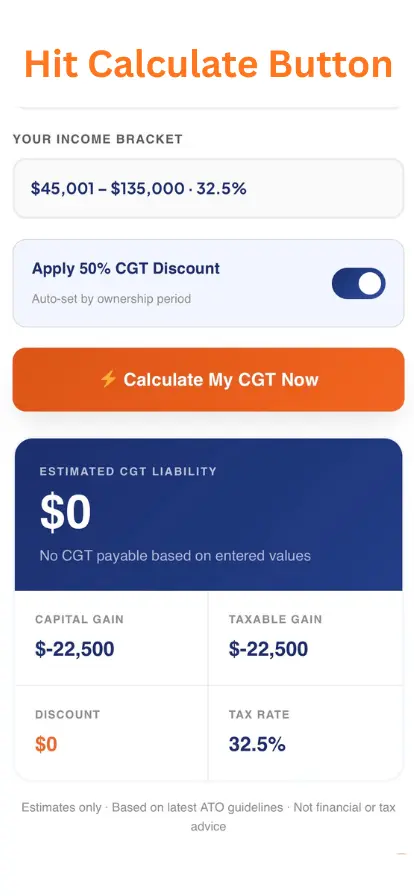
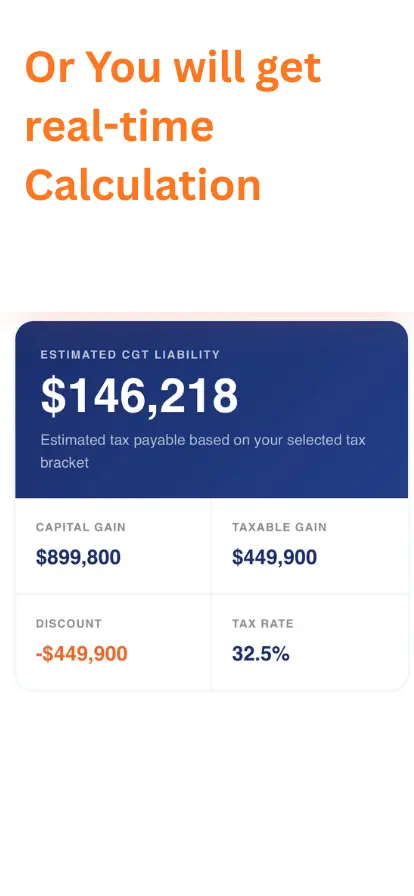
Here's the guide on ''How to use CGT Calculator''
These images shows ''How to use CGT Calculator accurately''
CGT Calculator Formula & ATO Methods
The ATO uses three methods to calculate CGT. Our CGT Calculator automatically selects the correct one based on your inputs.
Capital Gain
=Sale Price − Cost Base
Sale Price
The total amount received when selling the asset, including any deposits or part payments.
Cost Base
Total spent on purchasing, owning and selling stamp duty, legal fees, renovations, agent commissions.
METHOD 01
Discount Method
Hold the asset for more than 12 months as an individual or trust and claim a 50% CGT discount CGT Calculator apply this automatically). Only half the capital gain is added to your taxable income. The most commonly used method.
METHOD 02
INDEXATION METHOD
Applies only to assets acquired before 21 September 1999. The cost base is adjusted for inflation using the Consumer Price Index (CPI).
METHOD 03
Other Method — No Discount
If held under 12 months, or the asset is held by a company or certain trusts, no discount applies CGT Calculator determine automatically if you're eligible for discount or not). The full gain is taxed at your marginal rate.
Capital Gains Tax Rates in Australia
There is no separate CGT rate in Australia. Your capital gain is added to your taxable income and taxed at your marginal income tax rate.
Source: ato.gov.au · Current financial year · Medicare levy of 2% applies additionally
Your capital gain is not taxed at a flat rate. It is added to your other income — wages, rent, business income — and the combined total is taxed at the relevant bracket for that financial year.
For example, earning $90,000 from your job and making a $100,000 taxable capital gain brings your total to $190,000 — pushing a portion into the 45% bracket.
Worked Examples
Two complete CGT calculations, one for investment property, one for shares.
Investment Property
Held 3 years · 50% discount applies
Sale Price
$900,000
Cost Base
$608,000
$550k + $25k stamp duty + $15k renos + $18k selling costs
Capital Gain
$292,000
$900,000 - $608,000
After 50% Discount
$146,000
$292,000 ÷ 2
Added to Taxable Income at 32.5%
$146,000
Estimated CGT
~$47,450
at 32.5% marginal rate
ASX Shares
Held 18 months · 50% discount applies
Sale Price
$50,000
Cost Base
$30,200
$30,000 + $200 brokerage fees
Capital Gain
$19,800
$50,000 - $30,200
After 50% Discount
$9,900
$19,800 ÷ 2
Added to Taxable Income at 32.5%
$9,900
Estimated CGT
~$3,218
at 32.5% marginal rate
Assets Exempt from CGT
Not all assets trigger a CGT liability. The ATO provides exemptions that may fully reduce your obligation.
Main Residence
Your family home is generally fully exempt from CGT if you have lived in it the entire time you owned it.
The 6-Year Rule
If you move out and rent your home, you may treat it as your main residence for CGT purposes for up to six years.
Motor Vehicles
Cars, motorcycles and similar personal vehicles are exempt from CGT regardless of profit made on sale.
Personal Use Assets
Assets valued under $10,000 at acquisition and used mainly for personal purposes.
Pre-CGT Assets
Assets acquired before 20 September 1985 are generally not subject to CGT.
Compensation
Compensation received for personal injury or illness is exempt from CGT under ATO rules.
You can also check latest ATO rules from here.
Other CGT Calculators
Need a more specific calculation? Choose from our full suite of asset-specific and state-specific CGT Calculator.
By Asset Type
By State
Frequently Asked Questions
Everything you need to know about CGT Calculator in Australia
Not sure what you owe?
Enter your figures and get a precise CGT estimate in under two minutes. Aligned with latest ATO guidelines. Completely free.